Introduction
Midstream energy infrastructure equities, a conviction theme for the TwinFocus Investment Team over the past few years, have delivered strong performance again in 2026, with North American midstream equity returns approaching 30% year to date. Notably, that strength has been driven by fundamental improvements across the energy infrastructure landscape, rather than movements in oil and natural gas prices.
Our latest note examines the forces supporting the sector, including growing LNG export demand, the accelerating power requirements of data centers and AI, earnings that beat guidance, and continued dividend growth. We also examine current valuations, which have risen but remain below those of the broader equity markets.
Looking forward, midstream energy continues to be supported by powerful secular trends, from rising electricity consumption and AI-driven power demand to growing global demand for secure, diversified energy supplies. Together, these offer a potentially compelling combination of income, growth, and long-term infrastructure exposure.
In this whitepaper we provide our latest perspective on why midstream energy may offer an increasingly compelling combination of income, growth, and long-term infrastructure exposure.
In this whitepaper we provide our latest perspective on why midstream energy may offer an increasingly compelling combination of income, growth, and long-term infrastructure exposure.
Executive Summary
- The Alerian Midstream Energy Index (AMNAX), a broad-based composite of North American energy infrastructure companies, has returned +27.6% YTD through 8/21/2026, while the Alerian MLP Infrastructure Index (AMZI), a composite of energy infrastructure Master Limited Partnerships (MLPs), has returned +29.3%, extending positive annual returns of the past several years.
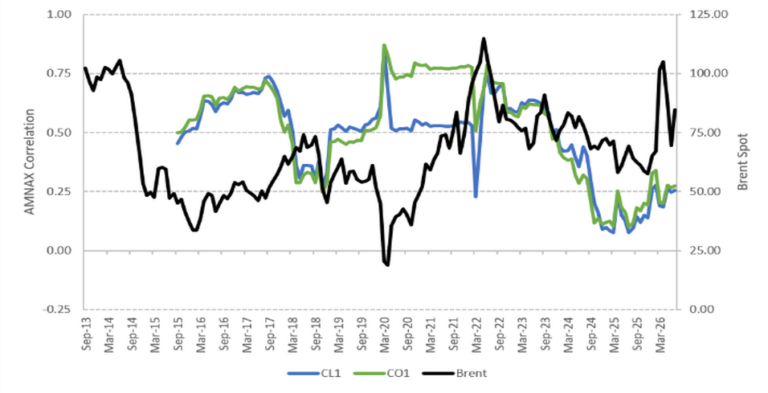
- Correlation of returns to commodity prices have fallen below the long-run averages as midstream returns have trended higher while oil prices swung with geopolitical risks and natural gas prices eased as supply has outpaced demand.
- Returns have been driven by fundamentals rather than commodity prices: LNG-export and datacenter power demand supported solid fundamentals that beat expectations with rising guidance and continued dividend growth.
- Midstream valuations have risen but remain below the broader equity market. AMNA now trades above while AMZI trades in line with their long-term averages.
- Longer-term midstream is expected from rising electricity consumption driven by electrification and AI demand, global buyers seeking secure and diversified energy supply and the eventual replenishment of strategic petroleum reserves.
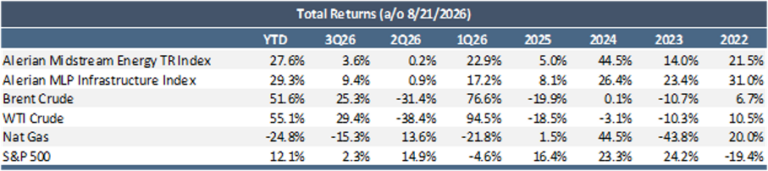
Source: Bloomberg
We continue to recommend active exposure to broad midstream energy sector, rebalancing back to strategic target given near-term uncertainty. Long-term, midstream companies stand to benefit from ongoing energy demand. Shorter-term, commodity prices may remain volatile due to geopolitical risks while midstream valuations have risen. The upside case, continued demand supporting strong fundamentals and higher multiples, appears partly priced in, suggesting maintaining rather than adding exposure and active over passive strategies.
Commodity Market Review
Oil prices have been volatile, whipsawed by geopolitical risks around the reopening of the Strait of Hormuz, while natural gas prices eased as supply has outpaced demand.
Oil prices have moved with the uncertainty around the (re)opening of the Strait of Hormuz; prediction markets place the odds of reopening by 12/31 at 42% (Polymarket) and 76% (Kalshi). Brent oil has risen +51.6% YTD, soaring +76.6% in 1Q, dropping -31.4% in 2Q before rebounding +25.3% 3Q through 8/21/26. WTI has been similarly volatile, up +55.1% YTD, rising +94.5% in 1Q, sinking -38.4% in 2Q and reversing +29.4% in 3Q.
While oil prices are higher YTD, they have settled below the level may expected with several potential mitigating factors:
- On again / off again negotiations, and potential of a soon-to-be-formalized memorandum of understanding to de-escalate tensions and reopen the Strait of Hormuz supporting expectations and capping prices.
- Inventory releases, with the IEA announcing a coordinated strategic reserve release of 400 million barrels with the US announcing the release of 172 million barrels.
- Demand destruction from measures last seen during COVID, e.g., rationing, school closures, work-from-home mandates.
- China cut oil imports 50%, lowering demand, e.g., cutting refining operating rates, while drawing on reserves and accessing alternative energy sources as part of its push for energy independence.
Natural gas spot prices followed the inverse path, down -24.8% YTD, falling -21.8% in 1Q, recovering +13.6% in 2Q then dropping -15.3% in Q3. The weakness reflects below expectations demand that was outpaced by supply growth.
- Total gas demand, including exports rose +2.5% y/y through July, driven by LNG feedgas and power burn, while production rose +4.3% y/y with storage nearly 7% above the 5-year average. Preliminary data from Rystad Energy forecasts 2026 average annual daily production up +4.7% y/y against demand growth of nearly +3.0%.
- Permian basin associated gas is a byproduct of oil production, making it inelastic to gas prices with the EIA now expecting record US oil production in 2027 with higher WTI prices.
- AI demand is arriving more slowly than expected with demand contracted forward into 2028–2030 while supply is current.
Midstream Energy Review
Midstream companies are largely toll takers, paid on volumes and contracted capacity, benefitting from flows rather than price.
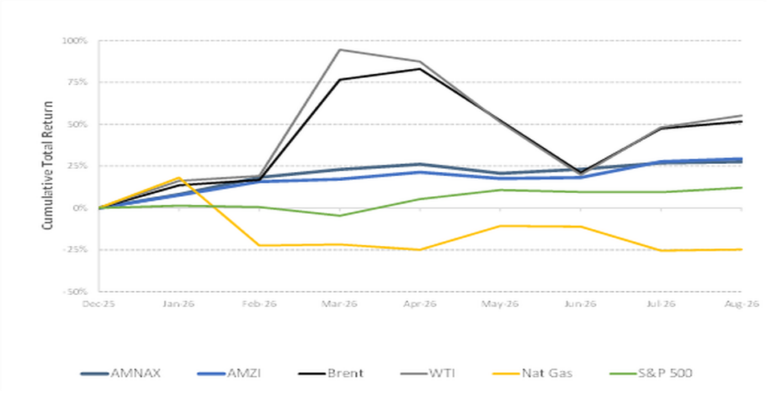
Through 8/21/2026, AMNAX returned +27.6% YTD and AMZI returned +29.0%, supported by strong fundamentals:
- Companies guided to mid-single-digit EBITDA growth entering the year and generally beat expectations while raising guidance.
- Distributions were steady, with growth primarily from MLPs as the majority of C-corps maintained their dividends. No index constituents has cut its regular dividend since 2021.
- Buybacks activity continues to complement dividends, though it is dominated by the larger index companies, with 7 constituents repurchasing an aggregate $856M, led by Cheniere at $500M.
Source: Bloomberg
The performance difference reflects the differing composition of the indices.
- AMNAX has exposure to Canadian companies (~25% allocation) and is skewed towards natural gas with sub-sector exposures of ~45% to natural gas transportation, ~25% gathering & processing, 10% liquefaction and only ~20% to petroleum transportation.
- AMZI is fully allocated to US companies with lower natural gas transportation (~20%) and higher petroleum transportation (~24%) and marketing & distribution (~18%) sub-sector exposure.
Correlations have fallen below long-term averages in 2026.
- The rolling 2-year correlation of midstream returns is +0.27 to Brent and +0.28 to WTI. This compares to longer-term correlations of +0.50 to Brent and +0.57 to WTI.
Source: Bloomberg
- The rolling 2-year correlation of midstream returns to natural gas has turned negative (-0.03) compared to the longer-term average of +0.20.

Source: Bloomberg
Valuation
Valuations have risen, remaining reasonable relative to the broader equity markets, but multiple and yields tell a mixed story, suggesting maintaining rather than adding exposure.
AMNAX is trading above its longer-term average Price to EBITDA ratio, while AMZI is trading in line.

Source: Bloomberg, TwinFocus
Chickasaw, the investment manager of MainGate MLP Fund, reports that the weighted average price to discounted cash flow and weighted average enterprise to EBITDA of its model portfolio remain below their long-term averages.
Yields have moderated since the start of the year. VettaFi, which owns and administers the Alerian indices, reports (as of 8/7/2026) a yield of 6.7% for the AMZI and 4.4% for the AMNAX against a 10-year average MLP yield of 8.5%.
Outlook
Midstream is expected to benefit from rising electricity consumption driven by electrification and AI demand with additional potential demand form global buyers seeking secure and diversified energy supply as well as the eventual replenishment of strategic petroleum reserves.
- The EIA estimates US electricity consumption growth of about +1.7% annually 2020-26, increasing from +0.1% annually from 2005-19, driven by electrification and AI hyperscalers. Growth is expected to continue though the long-term outlook projects a slower 0.9–1.6% annual pace through 2050.
- Less expensive natural gas arguably benefits midstream throughput and fundamentals as lower input costs support gas-fired power production and LNG volumes.
- Natural gas is the largest single source of US electricity generation, at roughly 39-40%, with the expectation of further demand from AI hyperscalers. The wildcard will be the pushback against data center development. In early August, Texas announced a pause on new data center development with the EIA lowering its projected 2027 Texas electricity load growth to 6% from 14%.
- The administration authorized a maximum release of 172 million barrels in March and has released an estimated 120 million barrels to date, bringing the SPR to ~293 million barrels, the lowest level since 1983, relative to 714 million barrels authorized capacity.
Conclusion
Midstream has extended its run of positive annual returns, supported by strong fundamentals rather than commodity prices. The fee-based model, paid on volumes and contracted capacity, held up through volatile oil and falling gas prices, as structural demand remains intact. The sector has re-rated with valuation metrics rising and yields easing relative to longer-term averages. We recommend maintaining exposure, expressed through active exposure, at strategic targets.
Memorandum Disclaimers & Disclosures
This Memorandum is confidential and may contain legally privileged and proprietary information of Twin Focus Capital Partners LLC (“TwinFocus”). It is intended solely for the use of the Recipients to which it is addressed. If you are not the intended recipient, you are hereby notified that any dissemination, copy, disclosure, use or action taken based on this Memorandum or any information herein is strictly prohibited and may be unlawful. If you received this Memorandum in error, please contact the sender immediately and destroy the material in its entirety, whether electronic or hard copy.
This Memorandum may not be otherwise redistributed, retransmitted or disclosed, in whole or in part, or in any form or manner, without the express written consent of Twin Focus Capital Partners LLC.
Investments involve numerous risks, including, among others, market risk, counterparty default risk and liquidity risk. In some cases, securities, strategies and other financial instruments may be difficult to value or sell and reliable information about the value or risks related to the security, strategy or financial instrument may be difficult to obtain. Income from such securities, strategies and other financial instruments, if any, may fluctuate and that price or value of such securities, strategies and instruments may rise or fall and, in some cases, investors may lose their entire principal investment. Foreign currency rates of exchange may adversely affect the value, price or income of any security or financial instrument mentioned in this Memorandum. Investors in such securities and instruments effectively assume currency risk. Additionally, before investing in any mutual fund strategies, Recipients are advised to obtain and closely review prospectuses and related information for those strategies before making any final investment decision.
Hedge fund and other alternative investments are generally unregulated and considered inherently very risky and you can lose material portions of your principal in very short periods of time. Prior to making any investments in any hedge fund managers and alternative investment strategies, you should thoroughly review all subscription documents and confidential offering memoranda provided by the managers/strategies, paying particular attention to the risk disclosures. You should not invest in such managers/strategies if you are not thoroughly comfortable with these risk disclosures or do not understand and/or appreciate the increased levels of risks associated with such strategies. Additionally, this Memorandum may provide information regarding private funds/strategies/investments which are exempt from registration under the Investment Company Act of 1940 pursuant to Section 3(c)(1) and/or 3(c)(7) which were offered as private placements in reliance on Regulation D of the Securities Act of 1933. Each individual fund/strategy and NOT TwinFocus shall have the sole responsibility for (i) formally qualifying prospective investors to ensure they meet the suitability criteria to invest in each relevant fund/strategy and, once qualified, (ii) sending the formal offering documents and other materials to each prospective investor.
Any information relating to the tax status of financial instruments and/or strategies discussed herein is not intended to provide tax advice or to be used by anyone to provide tax advice. Recipients are urged to seek tax advice based on their particular circumstances from an independent tax professional. Any waiver by TwinFocus of any section of this Memorandum Disclaimer Statement should not be construed as a general waiver of any other section and/or the entire Memorandum Disclaimer Statement.
The information, including but not limited to forecasts and estimates, in this Memorandum was obtained from various sources and TwinFocus does not guarantee its accuracy. Although the information contained in this Memorandum are from sources believed to be reliable, no representation or warranty, expressed or otherwise, is made to, and no reliance should be placed on its fairness, accuracy, completeness or timeliness.
All opinions, projections and estimates are as of the date of the Memorandum and are subject to change without notice. TwinFocus is under no obligation to update this Memorandum and Recipients should therefore assume that TwinFocus will not update any fact, circumstance or opinion contained in this Memorandum unless specifically requested. TwinFocus and any director, officer or employee of TwinFocus do not accept any liability whatsoever for any direct, indirect or consequential damages or losses arising from any use of this Memorandum or its contents.
This Memorandum may contain current opinions of third-party authors and not necessarily those of TwinFocus. Such opinions are subject to change without notice.
This Memorandum may contain references to market indices. Such information is presented to show the general trends in certain markets for the periods indicated and is not intended to imply that the strategy(s) discussed and/or reviewed are similar to the indices either in composition or element of risk. TwinFocus does not make any representations as to whether the indices may or may not be unmanaged, not investable, have any expenses and may or may not reflect reinvestment of dividends and distributions. Index data is provided for comparative purposes only. A variety of factors may cause an index to be an inaccurate benchmark for a particular portfolio/manager/strategy and the index does not necessarily reflect the actual investment strategy of the portfolio/manager/strategy discussed and/or presented in the Memorandum. Current period returns may be estimates. Actual index returns and/or estimates are calculated and presented to TwinFocus through third party software providers and as such, may differ from the final figures produced by the index provider.